Before You Renew: An E-Bike Insurance Reality Check for Harrogate Riders
Walk through Harrogate town centre on a Saturday and the same scene repeats: a row of e-bikes locked to the stands outside the station, a couple more parked up near a café on West Park, and at least one rider squinting at an insurance quote on their phone. The advert said cover from a few pounds a month. The small print said something rather different. For anyone buying or renewing e-bike insurance in 2026, the useful skill is not finding the cheapest quote. It is reading the policy like someone who might actually need it.
The Quote Is a Headline, Not the Story
Insurance websites are good at three things: a low monthly figure, a reassuring photograph of a cyclist, and a list of benefits in bold. What they are less good at is telling you when the payout will be reduced, delayed or refused. Before you compare prices, compare the definitions. What counts as an e-bike? Is it a pedal-assist model limited to 15.5mph and 250W, or has it been derestricted? If you have a throttle or a motor that keeps pulling after you stop pedalling, you may be outside the cover entirely. That matters in Harrogate, where the difference between a legal commuter bike and a modified one is often a diagnostic plug and ten minutes in a bike shop.
Theft: The Lock, the Location and the Wording
Most theft claims fail on one of three points: the lock, the place, or the proof. Insurers often specify an approved lock—usually Sold Secure Gold or better—and they may require it to be used in a particular way. A cable lock through the front wheel is not the same as a frame lock secured to a ground anchor. If your policy says the bike must be locked to an immovable object, a wooden fence post or a wheel-bender rack may not count.
Harrogate town centre adds its own complications. The cycle stands near the station and along Cambridge Street are convenient but busy. A thief with bolt croppers does not need long. If you leave an e-bike there for a full working day, check whether your cover has a time limit for unattended parking or a requirement to use a designated cycle park. Some policies also reduce the payout if the bike was left overnight in a public place. That is not a reason to avoid cover. It is a reason to read the conditions before you assume the shed at home is the only risk.
Damage and the Harrogate Grit Problem
Accidental damage cover sounds straightforward until you read the exclusions. Many policies cover a collision or a dropped bike, but not wear and tear, and not damage caused by a gradual process. Winter in Harrogate is a gradual process. Grit on Otley Road, wet leaves on the stray paths around the Stray, and the salt that gets into a chain and a battery mount can all shorten a bike's life without producing a single dramatic incident.
If you claim for a corroded battery terminal or a water-damaged controller, expect questions. Was the bike serviced? Was the battery removed and stored correctly? Did you leave it in a damp garage? Some insurers will pay for storm damage or a sudden impact, but not for the slow decay that comes from riding through a Yorkshire winter without mudguards. Keep receipts for servicing and take photographs of the bike before and after a claim. A dated photo of your battery mount in October is worth more than a long argument in January.
Battery Fires, Water Ingress and the Exclusion You Did Not Read
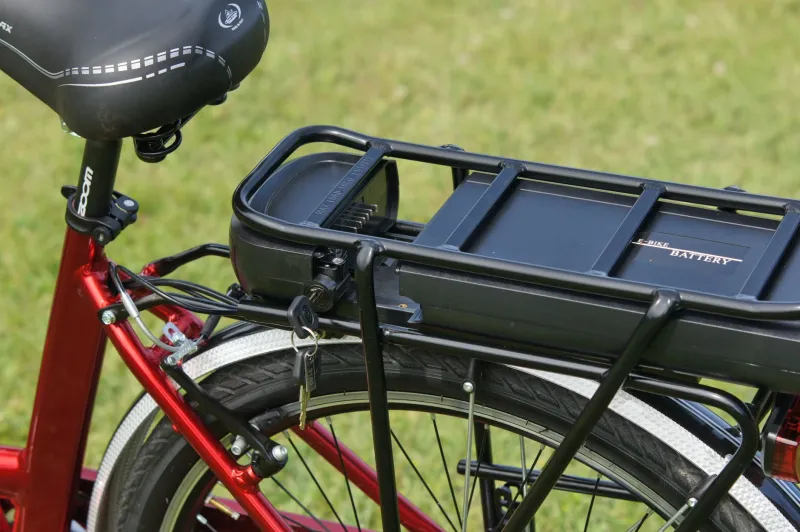
Battery damage is the quiet exclusion in many e-bike policies. A cracked casing from a fall might be covered. A battery that has been charged with the wrong charger, left in a hallway, or submerged in a flooded lane may not be. Lithium battery fires are rare, but they are serious enough that insurers now ask where you charge. If you live in a flat above a shop on Parliament Street and charge your battery in the communal hallway, your home insurer may have something to say about it. Your e-bike policy may too.
Water ingress is another grey area. A ride along the Nidderdale Greenway in November is not an extreme sport, but a deep puddle near Ripley can force water into places the manufacturer never intended. Some policies treat water damage as accidental damage. Others class it as neglect. Check which one applies before the puddle, not after.
Liability: The Quiet Part That Matters
Third-party liability is the cover most riders ignore until they need it. If you clip a pedestrian on a shared path or roll into the back of a car at a junction, the cost can be significant. E-bike insurance often includes public liability, but the limit varies wildly. A policy with £1 million of cover may sound generous until you compare it with the cost of a serious injury claim. Look for at least £2 million, and check whether the cover applies while you are commuting, riding for leisure, or using the bike for work.
Home Insurance Is Not a Substitute
It is tempting to assume your contents policy already covers the e-bike. Sometimes it does. Often it does not. Standard home insurance may exclude bikes over a certain value, or cover them only while they are at home. Theft away from the property may be limited or excluded. If you do add the bike to your home policy, check the excess and whether the insurer requires the same approved lock. A separate e-bike policy is not always cheaper, but it is usually clearer about what happens when the bike is stolen from a rack in Knaresborough while you are buying a coffee.
A Pre-Purchase Checklist for 2026
Before you pay for cover, ask five questions. First, what is the maximum payout for theft, and is it new-for-old or market value? Second, which locks are approved, and do you need to carry a specific one? Third, is accidental damage included, and what is excluded as wear and tear? Fourth, what is the liability limit, and does it cover commuting? Fifth, what happens to the battery—is it covered for fire, water and theft, or is it treated separately?
Then do one local thing: read the policy with your actual routine in mind. If you commute from Bilton to the station, lock up in town and ride the Greenway at weekends, the policy needs to fit all three. If you leave the bike in a shared garage in Starbeck, say so. Insurers dislike surprises, but they dislike undisclosed facts even more.
Insurance will never make a stolen bike feel less annoying. It can, however, turn a miserable week into a manageable one. The trick is to treat the quote as the beginning of the conversation, not the end of it. In Harrogate, with grit on the road and a train to catch, that is worth the extra ten minutes.